Professional Liability Insurance, often associated with Errors & Omissions (E&O) coverage, is designed to address certain claims alleging that professional advice, services, work, or duties resulted in a client’s financial loss or other covered harm.


An allegation that an error occurred while providing professional services.

An allegation that an important professional action, responsibility, or detail was missed.
An allegation that advice, recommendations, or professional judgment caused a client loss.

A client alleges that professional work contributed to a financial loss.

A dispute involving the performance or delivery of professional services.
An allegation that professional duties were not performed with the expected level of care.

Certain expenses involved in responding to covered claims.
Allegations made by clients arising from covered professional services.
Certain claims involving alleged errors in professional work.
Certain claims involving alleged omissions or missed professional duties.
Certain allegations involving professional negligence.
Where applicable and subject to the policy’s terms, conditions, limits, and exclusions.
A professional claim may create financial exposure through legal, defense, response, settlement, or other costs, depending on the circumstances and applicable coverage.
Responding to a professional claim can require time, legal resources, documentation, and professional attention.
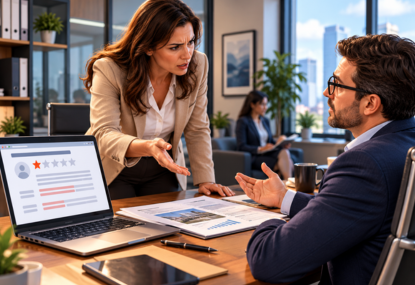
A dispute may also affect client relationships, trust, referrals, and professional reputation.
What advice, expertise, treatment, design, technology, or other services do you provide?
Do contracts require specific insurance, limits, or terms?
Are there regulatory, licensing, contractual, or industry expectations?
How much does the client rely on your professional judgment or recommendations?
Does your work involve systems, sensitive information, digital delivery, or technology dependence?

What is the scale, complexity, client mix, and potential financial impact of a claim?
Professional Liability Insurance may help eligible professionals and businesses address certain claims alleging errors, omissions, negligence, or other problems related to professional services. Coverage depends on the specific policy, its terms, conditions, limits, and exclusions.
It may be relevant to professionals and service businesses whose clients rely on their advice, expertise, judgment, or specialized services, including consultants, healthcare professionals, lawyers, architects, designers, and technology professionals. Needs vary by profession and business.
Depending on the policy, it may help address certain claims involving alleged professional errors, omissions, negligence, advice, or client financial loss arising from covered professional services. Specific coverage is determined by the policy.
No. These policies address different types of risk. Professional Liability generally focuses on certain professional-service allegations, while General Liability may address certain third-party injury or property-damage exposures and Cyber Insurance may address certain cyber, data, privacy, and related exposures. A business may need more than one type of coverage.
Factors can include the type of professional services provided, client contracts, industry requirements, advice or expertise involved, technology and data exposure, business size, and overall risk profile. A specialist can help evaluate which factors are most relevant to your situation.
Discuss your profession, services, clients, and insurance questions with a specialist.
Review coverage options that may fit your business and professional risk profile.
Get help navigating the information and enrollment steps required for the selected policy.
Continue to receive guidance as your business and insurance needs evolve.
Loans and withdrawals may reduce cash value and death benefit, affect policy status and may have tax consequences. Review your policy details.


Copyright 2026 OLPolicy - All Rights Reserved.
 contact@olpolicy.com
 (866) 757-5350