Term Life Insurance provides life insurance protection for a specific period. It may help provide financial support for loved ones if something happens during the covered term, subject to the policy’s terms and conditions.
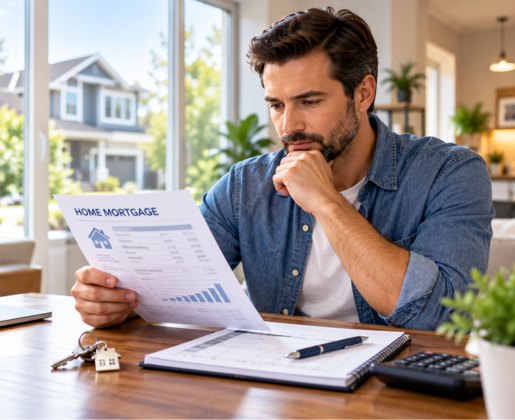
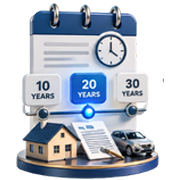
Term Life Insurance provides coverage for a specified period, such as 10, 20, or 30 years, depending on the policy. If the insured person dies during the covered term, the policy may provide a death benefit to the named beneficiaries, subject to the policy’s terms, conditions, and exclusions.
Term Life Insurance is often considered for time-limited financial needs, such as supporting dependents, replacing income, or helping address outstanding financial obligations.
Determine an appropriate coverage amount based on financial responsibilities, dependents, and goals.
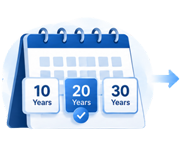
Select a policy term that fits the period for which protection is desired. Common options may include 10, 20, or 30 years, depending on the policy.
Pay the required premiums according to the policy to keep coverage in force.
If the insured dies while the policy is in force during the covered term, a death benefit may be payable to beneficiaries, subject to policy terms and conditions.
Coverage is designed for a specific policy period, helping address financial needs that exist during a defined stage of life.
Term coverage may have lower premiums than some permanent life insurance options, depending on the policy and applicant.
A death benefit may help beneficiaries address financial responsibilities if the insured dies during the covered term
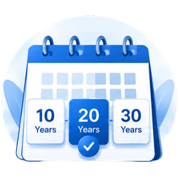
Depending on the policy, term lengths may include options such as 10, 20, or 30 years.
Term Life Insurance focuses on life insurance protection for a specified period rather than building a cash-value component
People beginning their careers who want to consider protection for future financial responsibilities.
Individuals whose income supports a spouse, children, or other dependents.
Parents who want to consider financial protection during years when children may depend on household income.
Individuals who want to consider how outstanding financial obligations could affect loved ones.
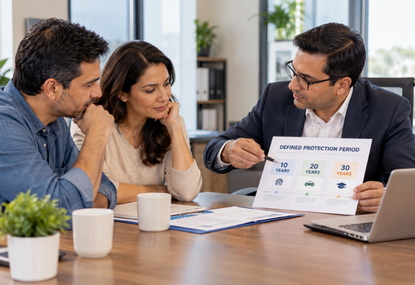
Those whose primary need is protection during a defined period rather than permanent coverage.
Consider the financial responsibilities you want the policy to help address
Consider how long protection may be needed based on your life stage and obligations.
Consider whether the premium fits comfortably within your budget.
Consider who may rely on your income or financial support.
Consider mortgages, debts, education costs, and other major responsibilities.
Review exclusions, renewal provisions, conversion provisions, and other policy-specific details where applicable.
Discuss financial responsibilities, goals, and the desired protection period
Explore available Term Life Insurance options that may align with your needs and budget.
Get help understanding coverage amounts, term lengths, premiums, and key policy provisions.
Make an informed decision based on your circumstances, priorities, and available policy terms.
Term Life Insurance provides life insurance protection for a specific period, such as 10, 20, or 30 years, depending on the policy. If the insured dies during the covered term, a death benefit may be payable to beneficiaries, subject to the policy’s terms, conditions, and exclusions.
You select a coverage amount and policy term, then pay the required premiums according to the policy. Coverage applies during the policy term while the policy remains in force. A death benefit may be payable if the insured dies during the covered term, subject to policy terms and conditions.
Available term lengths vary by policy and applicant. Common options may include 10, 20, or 30 years. The appropriate term depends on financial responsibilities, life stage, and the protection period you want to consider.
Term Life Insurance is designed to provide protection for a specified period and typically does not include a cash-value component. Whole Life Insurance is generally designed as permanent coverage and may include a cash-value component. Features, premiums, and policy provisions vary.
Term Life Insurance may be worth considering for people with time-limited financial responsibilities, such as supporting dependents, replacing income, covering a mortgage or other obligations, or protecting loved ones during a defined stage of life.


Copyright 2026 OLPolicy - All Rights Reserved.
 contact@olpolicy.com
 (866) 757-5350